Regulated by The Property Ombudsman. We cover every fee. Call us today: 0141 673 3770

Home / Situations / Stopping repossession

Stopping repossession

Behind on the mortgage? You may still have options.

If your lender has started court action, it can feel like the decision has been taken out of your hands. Often it has not. Selling before the lender takes control can protect the equity you have built and let you leave on your own terms rather than theirs. We help calmly, quickly, and without pressure, anywhere in Scotland.

Get my cash offer →

Before anything else, please speak to a free debt adviser. StepChange and Citizens Advice Scotland both give free, confidential, independent advice, and can talk to your lender for you. National Debtline is another free option. Selling is not always the right answer, and good advice costs you nothing. We would rather you knew all your options than felt rushed into one.

Why timing matters here

Selling yourself usually protects more than a forced sale.

When a lender repossesses and sells, they aim to clear the debt, not to get you the best result. Costs, arrears and legal fees come off the top, and anything left is what reaches you. Selling before that point often means you keep more of your own equity.

  • You stay in control of the sale, not the lender
  • Repossession stays off your credit file
  • Court and legal costs stop adding to the debt
  • Any equity left is protected rather than eroded
stock
How we help in this situation

Three steps, moving at the speed your deadline needs.

If you have a court date, tell us. We work honestly to your real timeline, and we never invent one to hurry you.

01
📞

A quick, honest conversation

Tell us where things stand: the arrears, any court date, what your lender has said. We give you a cash offer within 24 hours so you know exactly what is on the table, with no obligation to take it.

02
✉️

We can speak to your lender

Lenders will often pause action when they can see a genuine sale is agreed. With your permission we can share proof of a firm offer and a completion date, which can be the evidence that buys you room.

03
✅

Complete before the lender acts

Typically complete in 14 to 28 days on a cash purchase when your deadline is tight. The mortgage is cleared from the sale, and any equity left is paid to you.

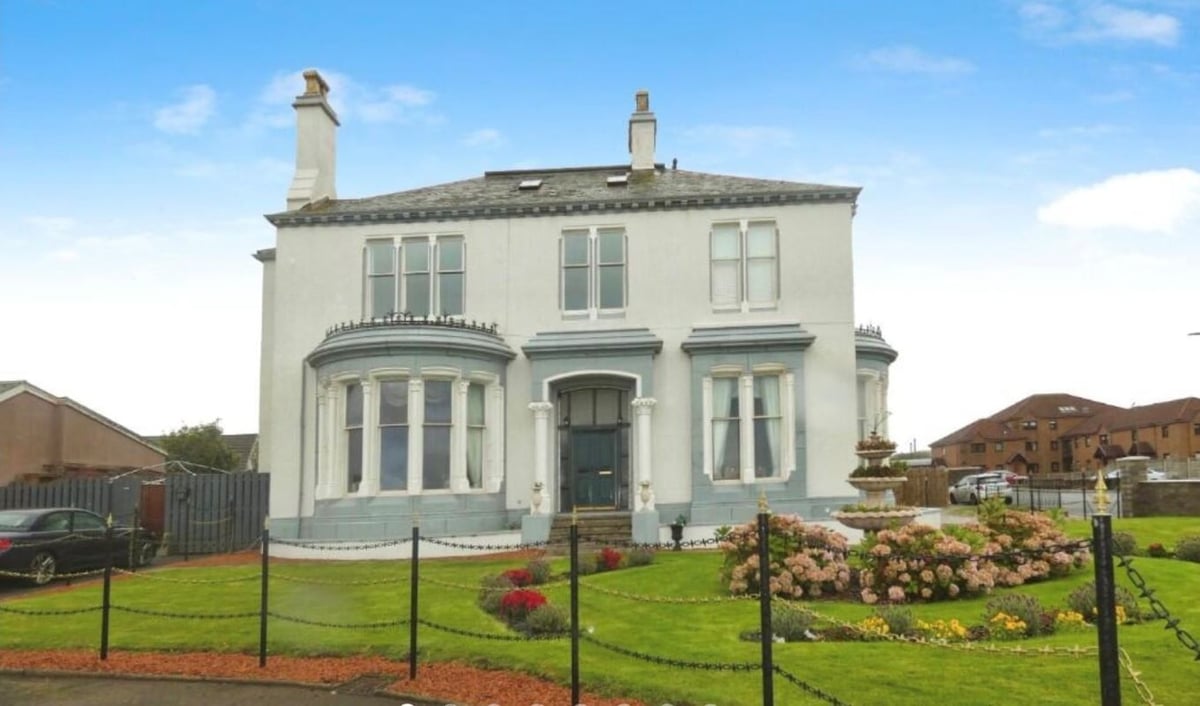
ayr
A real story

A court date, and time running short.

A homeowner had fallen behind after losing work and had a repossession hearing weeks away. We gave a firm offer within 24 hours, evidenced it to the lender, and completed before the court date. The mortgage and arrears were cleared, and the remaining equity went to the seller rather than being lost to a forced sale.

  • The real deadline was the court date, and we worked to it honestly
  • Equity protected instead of eroded by costs
  • Repossession avoided, and off the credit file
Read more seller stories →
Why people facing repossession choose us

Support first, sale second.

🫂

No pressure, no judgement

Money worries can happen to anyone, and they are nothing to be ashamed of. We listen first, explain your options plainly, and let you decide. If selling is not right for you, we will say so.
⏱️

Fast when it needs to be

When a deadline is genuinely close, speed is everything, and a guaranteed cash sale is the most certain route. We move as quickly as your situation truly requires, never faster than your comfort.
🛡️

Regulated by The Property Ombudsman

We are regulated by The Property Ombudsman, which sets a clear code of conduct. That protection matters most when you are vulnerable.
Repossession questions

What people facing repossession ask us.

Often, yes, if there is enough time. Lenders will frequently pause court action when they can see a genuine, evidenced sale is going through, because they recover the debt without the cost of repossessing. The closer your court date, the more speed matters, which is why we move quickly and can share proof of a firm offer with your lender. Speak to a free debt adviser too, as they can also negotiate with your lender on your behalf.
Not necessarily. A cash sale can complete in around 14 to 28 days, and even the existence of an agreed sale can give a lender reason to hold off. Tell us your actual court date and we will be honest about whether we can realistically complete in time. We will never pretend a deadline is closer than it is, and we will never invent one.
Please contact StepChange or Citizens Advice Scotland. Both offer free, confidential, independent debt advice and can talk to your lender for you. National Debtline is another free option. Getting proper advice first means any decision you make, including whether to sell at all, is one you have made with the full picture.
If your home is worth more than you owe, that difference is your equity, and after the mortgage and arrears are cleared from the sale, the remainder is paid to you. Selling yourself usually protects more of it than a forced sale by the lender, where costs and fees come off first. A cash offer is not the full open-market headline, and we say so honestly, but with every fee covered and no forced-sale costs eating into your equity, a quick certain sale can still leave you far better off than repossession. Below open-market value, with no fees to pay.

Talk to us before the lender decides for you.

A free, no obligation cash offer within 24 hours, and an honest conversation about whether selling is right for you. No pressure, and no judgement.

Get my cash offer →
Or call us on 0141 673 3770